

Pre-Loss Risk Surveys — Pakistan & the Gulf
The best claim is the one that never happens.
Risk surveys for underwriters and insured companies, written by people who investigate losses for a living. We look at a site the way we would after a fire, a breakdown or a collapse, and report the conditions most likely to produce the next claim.
Instructed by
Underwriters, brokers, insured companies
Focus
Conditions most likely to cause a loss
Perspective
From the investigation of real losses
Deliverable
Risk survey with prioritised improvements
Since the 1990s
30
years investigating
250+
investigations closed, incl. HiPOs
15
countries served
20+
countries of lead seminars
100+
nationalities trained
How an instruction runs
From notification to a report you can rely on.
Typical sequence for a major loss. Timing is agreed with you for each instruction.
1 · First call
The risk
We agree the site, the scope and who receives the survey.
2 · Walk-through
The site
Every area walked, across shifts where possible, as if after a loss.
3 · Fire load
Storage and separation
Combustibles, stacking, exits and separation between areas assessed.

4 · Electrical
Panels and hot work
Distribution panels, generators and hot work controls checked.
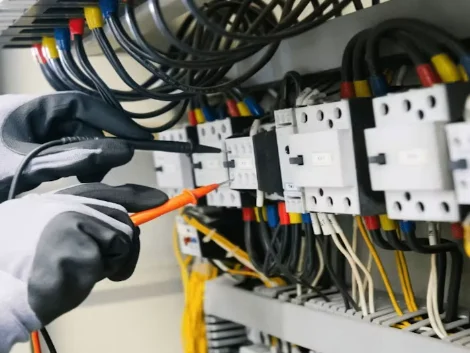
5 · Survey
Prioritised improvements
A survey report ranking the conditions most likely to cause a claim.
The questions insurers ask us
Choose the question. See how we answer it.

What we establish
Storage, layout, separation and the protection that is actually working.
Evidence we rely on
Walk-through, test records, fire plans.
Where we stop
Facts on one side. Decisions on the other.
Established by P3i
The sequence of events
The cause and contributing conditions
Whether stated controls were in place
What remains uncertain, stated plainly
Reserved to the insurer
Policy interpretation and coverage
Quantum and adjustment
Legal advice and proceedings
The relationship with the insured
A loss notified this week? A first call costs nothing, and we will tell you what should be preserved before the site is cleared.
Ways to instruct us
One loss, or your whole book.
a.Single instructionOne loss, one agreed scope and timeline.b.Panel appointmentAgreed scopes, response times and report formats across your book.c.Second lookAn independent review of a report you have received.d.Pre-loss surveyA risk survey written from real loss experience.
The P3i approach
How we investigate a loss for insurers. Fact-finding, not fault-finding.
Every P3i investigation is led by a senior investigator and supported by internationally qualified process specialists. You will not receive a list of people to blame, or a long list of generic actions. You will receive the facts, the proven causes, and a short plan that closes the gaps, in this case and across your system.
Independent
No products, repairs or contracts to sell you afterwards.
Senior-led
Thirty years of investigation, from the first call to the final briefing.
Beyond the event
Process specialists find the other cracks before they fail.
Ready to present
Written for boards, buyers, insurers and regulators.
How P3i does it for you
- 01
Survey like an investigator
Through the lens of real losses.
- 02
Walk every shift
Not just the tidy morning visit.
- 03
Test protection
Working, not just installed.
- 04
Rank what causes claims
Fire load, electrics, hot work, storage.
- 05
Report for underwriting
Prioritised improvements.
What you receive
Call us when
Free 30-minute case assessment.
Tell us what happened. In confidence, we will tell you what the investigation should cover, how long it will take and what to preserve today.
How we work with you
What happens after you call.
For an insurance instruction, the first call covers the loss, the parties involved, what must be preserved and the scope you need. From there, this is the usual pattern.
First hour
A call with a lead investigator. You leave it knowing what to preserve today and who to call next.
Day one
An investigator on site, anywhere in Pakistan. Scope and fixed fee agreed in writing.
Week one
A private briefing on early findings, so urgent risks are dealt with before the report is finished.
Weeks three to four
The final report, the wider system review and a remedial work plan, presented to your team.
After
We come back to check the actions were completed and actually worked.
Typical timings for a single-site event. Complex, multi-party matters take longer, and we tell you so on the first call.
What you receive
A full investigation report. This is only its first page.
The summary is what leadership reads first. Behind it sits the complete file: every witness heard, every document and record examined, and every finding tied to numbered evidence, so a board, an insurer, a buyer or a regulator can test it.
1 · Established sequence
2 · Causes
3 · Wider system findings
4 · Remedial work plan
Illustrative summary page. Report length and structure depend on the scope of each case.
Inside the full report
- 01Executive summary SHOWNThe findings and actions leadership needs, on one page. This is the page shown here.
- 02Terms of reference & scopeThe questions asked, the boundaries of the investigation and who commissioned it.
- 03MethodHow evidence was gathered, and which analysis methods were chosen for this case, and why.
- 04Verified chronologyThe sequence of events, reconstructed from records, data and accounts, minute by minute where it matters.
- 05Site & technical examinationScene, equipment, failed parts, measurements and photographs, with specialists where needed.
- 06Witness evidenceInterview schedule, accounts in summary, and where the witnesses agree and where they conflict.
- 07Documents & recordsPermits, procedures, maintenance, training, rosters, CCTV, tracker and control-system data reviewed.
- 08Causal analysisImmediate, underlying and system causes, each one tied to numbered evidence.
- 09System reviewWhere the same weaknesses exist elsewhere in the operation.
- 10Findings & conclusionsWhat is proven, what is probable, and what remains open, stated plainly.
- 11Recommendations & work planTargeted actions, each with an owner, a date and a test of whether it worked.
- 12AppendicesEvidence register, photograph log, interview records, drawings and data extracts.
Every action has an owner, a date and a test of whether it worked. The evidence stays indexed, so any reader can check how each conclusion was reached.
From our files
See all 16 cases → Client names, people, locations and dates removed.
Questions
What claims teams ask us first.
How is this different from a standard survey?
We survey through the lens of real losses we have investigated, so the findings focus on what actually causes claims.
Who receives the report?
Whoever instructs us: the underwriter, the broker or the insured.
Can you survey before renewal?
Yes. A survey before renewal gives both sides a clearer picture of the risk.